Your invoices are piling up, payroll is approaching, and last month’s bank transactions still haven’t been reconciled. Meanwhile, you’re spending hours organizing receipts instead of managing customers or growing your business.
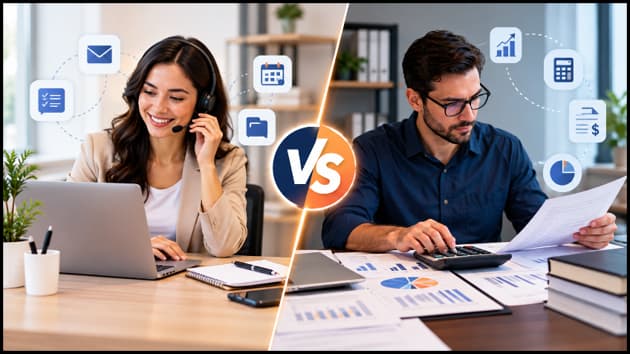
Hiring someone to help sounds reasonable. But should you choose a virtual assistant or a bookkeeper?
The difference comes down to responsibility. A virtual assistant handles administrative work and may support routine financial processes. A bookkeeper maintains financial records, reconciles accounts, and prepares information needed for accurate reporting.
Some businesses need one. Others benefit from both.
Understanding where their responsibilities overlap, and where specialized financial expertise becomes necessary, can help you avoid unnecessary costs and accounting mistakes.
What Should Businesses Know Before Outsourcing Payroll?
Outsourcing payroll can reduce administrative work, but businesses must understand their tax responsibilities.
According to the Internal Revenue Service (IRS), employers generally remain responsible for federal employment tax deposits and payments, even when a third-party provider manages payroll.
Before choosing a payroll service, verify how the provider handles tax filings, payment approvals, and compliance reporting. Regularly reviewing payroll records can help businesses identify errors before they become costly.
How a Virtual Assistant and Bookkeeper Can Support Your Business
Businesses looking for combined administrative and financial support can consider a virtual assistant and bookkeeper arrangement based on their workload.
An accounting-focused virtual assistant can organize invoices, maintain records, communicate with vendors, and support established bookkeeping workflows.
A dedicated bookkeeper provides the financial expertise required to reconcile transactions and maintain reliable accounting records.
Combining these functions allows business owners to delegate recurring work without expecting one employee to manage every financial responsibility.
What Does a Virtual Assistant Do in a Business?
A virtual assistant is a remote professional who manages administrative and operational responsibilities.
Depending on their training, assistants can handle email correspondence, scheduling, document management, customer follow-ups, and routine financial administration.
For example, a business receiving dozens of vendor invoices weekly might assign a virtual assistant to collect documents, verify required information, and organize invoices for approval.
Common responsibilities include:
- Organizing receipts and expense documentation
- Preparing invoices and payment reminders
- Maintaining customer and vendor records
- Entering approved information into accounting software
- Coordinating financial documents with accountants
A virtual assistant familiar with QuickBooks or Xero may also support transaction entry and established bookkeeping procedures.
However, software familiarity alone doesn’t establish accounting expertise.
What Does a Bookkeeper Do?
A bookkeeper records, organizes, and verifies a company’s financial transactions.
Their main responsibility is maintaining accurate records of money entering and leaving the business.
Unlike a general virtual assistant, a bookkeeper typically understands double-entry bookkeeping, account reconciliation, ledgers, and financial reporting requirements.
Responsibilities often include recording transactions, categorizing expenses, reconciling bank statements, monitoring accounts payable and receivable, and preparing routine financial reports.
Consider a retailer processing hundreds of monthly sales and supplier payments.
A bookkeeper ensures those transactions are recorded correctly and investigates discrepancies between the accounting system and bank statements.
A bookkeeper can prepare records for tax filing, although tax advice and certain filing responsibilities require appropriately qualified professionals.
Virtual Assistant vs. Bookkeeper: Key Differences at a Glance
| Factor | Virtual Assistant | Bookkeeper |
| Primary role | Administrative support | Financial recordkeeping |
| Invoice management | Creates and tracks invoices | Records and reconciles related transactions |
| Expense management | Organizes receipts | Categorizes and verifies expenses |
| Bank reconciliation | May assist with defined tasks | Typically performs and reviews reconciliations |
| Payroll | Collects timesheets and records | May prepare payroll records if qualified |
| Financial reports | Organizes supporting data | Prepares routine financial statements |
| Tax preparation | Collects documents | Prepares records for tax professionals |
| Best suited for | Recurring administrative workload | Accurate financial records |
The distinction matters because incomplete records and incorrect financial decisions create different risks.
A virtual assistant helps keep processes moving. A bookkeeper ensures financial transactions are properly accounted for.
Which Financial Tasks Should Businesses Outsource?
Small business bookkeeping outsourcing works best when owners separate routine administration from work requiring financial judgment.
Daily Bookkeeping and Invoice Processing
Virtual assistants can collect receipts, organize invoices, enter approved transaction details, and follow up on outstanding documentation.
Bookkeepers can then verify classifications, reconcile transactions, and investigate unusual balances.
This division reduces repetitive work without weakening financial oversight.
Payroll Processing and Wage Disbursement
Payroll outsourcing services can support wage calculations, tax withholding, reporting, and payment administration.
A virtual assistant might organize timesheets and employee information. A qualified payroll provider handles authorized payroll processing.
Outsourced wage disbursement requires stronger controls because it involves transferring employee compensation.
Businesses should retain approval authority and independently verify payroll reports.
Tax Preparation and Compliance
When businesses outsource tax preparation, assistants can collect supporting documents while bookkeepers maintain the underlying financial records.
Qualified tax professionals handle tax interpretations, preparation requirements, and filing responsibilities according to their credentials and applicable rules.
Third-party accounting firms can also provide specialized reporting, tax planning, and compliance assistance when internal expertise is limited.
How Do Administrative Assistant Salaries Compare?
According to the U.S. Bureau of Labor Statistics, secretaries and administrative assistants earned a median annual wage of $48,310 in May 2025.
These figures reflect U.S. employee wages, not outsourced virtual assistant rates.
Businesses primarily needing invoice organization, document preparation, and routine administrative support can compare virtual assistant pricing with the total cost of hiring an employee.
The lowest monthly price isn’t necessarily the most economical arrangement if inaccurate work requires expensive corrections.
A Financial Task-Ownership Framework Most Businesses Overlook
Before outsourcing financial work, determine who prepares information, who checks it, and who authorizes financial transactions.
A clear division of responsibilities can reduce errors and unauthorized activity.
| Task | Preparation | Verification or approval |
| Vendor invoices | Virtual assistant | Manager or authorized employee |
| Transaction records | Trained assistant or bookkeeper | Bookkeeper |
| Bank reconciliation | Bookkeeper | Owner or independent reviewer |
| Payroll changes | Authorized payroll staff | Designated manager |
| Tax filings | Qualified tax professional | Authorized business representative |
Important: The person preparing payments should not automatically have authority to approve and release them.
Use individual software accounts, multifactor authentication, restricted permissions, and documented approval procedures.
A small business doesn’t need a large finance department to establish these safeguards.
Frequently Asked Questions
1. Can a Virtual Assistant Do Bookkeeping?
Yes, a trained virtual assistant can handle routine bookkeeping tasks such as invoice entry, expense categorization, and receipt organization. However, complex reconciliations, financial reporting, and accounting decisions require appropriate expertise. Businesses should assess actual qualifications and assign independent reviews rather than assuming every administrative assistant can maintain accurate books.
2. Is It Safe to Outsource Payroll for a Small Company?
Payroll outsourcing can be safe when providers use secure systems, restricted access, documented approvals, and appropriate regulatory procedures. However, employers generally remain responsible for federal employment tax obligations. Business owners should review payroll reports, verify tax deposits, and investigate discrepancies instead of assuming the provider handles every liability.
3. Do Small Businesses Need Both a Bookkeeper and an Accountant?
Not always. A bookkeeper maintains transaction records and prepares routine reports, while an accountant provides additional expertise in financial reporting, taxes, and complex accounting decisions. Businesses with straightforward finances may use bookkeeping support throughout the year and consult an accountant periodically for specialized requirements.
Practical Steps to Choose the Right Financial Support
Before hiring, review where your team spends time and which financial responsibilities remain unfinished.
Start with three questions:
- Are administrative tasks delaying daily operations?
- Are financial records accurate and reconciled each month?
- Does your business need specialized payroll, tax, or accounting expertise?
If administration is the problem, consider a virtual assistant. If financial accuracy is the concern, prioritize bookkeeping expertise. If both areas need attention, divide responsibilities between qualified professionals.
Build the arrangement around your actual workload, establish clear approvals, and review performance monthly.
The right support structure should produce reliable records, clearer accountability, and fewer hours spent correcting avoidable mistakes.